
In today’s rapidly evolving digital era, conventional cash-based transactions are gradually fading into the background. As online and mobile payment solutions become more accessible, people around the world are shifting away from traditional banknotes and coins in favor of contactless, instant, and more convenient methods of settling their bills. One country that stands at the forefront of this transformative wave is China, where mobile payment platforms have taken center stage in everyday commerce. Within this dynamic environment, Alipay, a payment and lifestyle application originally developed under the umbrella of the Alibaba Group, has emerged as a dominant force shaping how Chinese consumers, merchants, and even tourists handle financial transactions.
At its core, Alipay exemplifies the immense potential of mobile payment platforms. It has grown from being a simple online escrow service for e-commerce transactions to becoming a sophisticated financial ecosystem that enables its users to pay for groceries, hail rides, order meals, manage their finances, invest in wealth management products, purchase insurance, and even access government services—often all within a single platform. More than just a payment tool, Alipay represents a paradigm shift in how societies can approach commerce and the provision of financial services, heralding a future where physical currency is no longer necessary.
However, beyond the convenience and sophistication, there are profound questions about security, regulatory compliance, innovation, inclusion, and the implications for cross-border visitors. As Alipay’s ecosystem expands and tightens its grip on the Chinese market, understanding the platform’s impact, functionality, benefits, and potential vulnerabilities has never been more crucial. This article will delve into how Alipay revolutionizes day-to-day payments, the drivers behind its widespread adoption, its role in improving financial inclusion, and how both merchants and consumers benefit from this continuously evolving mobile payment infrastructure. We will also explore key concerns regarding privacy, security, and regulatory oversight, as well as offering actionable tips to minimize risks when using QR codes and other digital tools.
A New Era of Mobile-First Transactions
The growth of digital payment systems in China has been nothing short of astounding. Over the past decade, consumers have shown a marked preference for using mobile wallets over cash or conventional credit cards. This surge is underpinned by the meteoric rise in smartphone adoption, government policies supportive of fintech innovation, and a combination of market competition and consumer demand for seamless payment experiences.
Alipay, launched in 2004 by Alibaba’s founder Jack Ma, started as a trusted payment intermediary for online shoppers and sellers on Alibaba’s e-commerce platforms like Taobao. Initially, it served as an escrow service to ensure that buyers received products as described before releasing funds to sellers. This functionality built trust in online transactions, boosting consumer confidence in digital payments. Over time, Alipay branched out from e-commerce facilitation into new areas, integrating an entire suite of financial services that now includes money transfers, bill payments, ride-hailing, utility bills, investment products, travel bookings, insurance, and more.
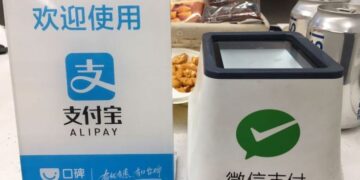
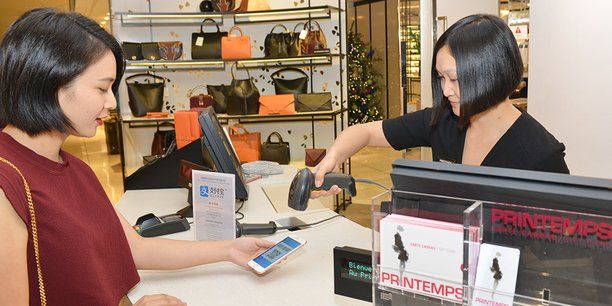
By the early 2010s, as smartphones and mobile internet access proliferated across the country, Alipay was perfectly positioned to capitalize on shifting consumer behaviors. Supported by China’s highly developed mobile infrastructure, robust network coverage, and increasing technological literacy, Alipay quickly transcended online platforms and made its way into offline transactions. Soon, physical merchants, from luxury boutiques to street food vendors, adopted Alipay’s QR code-based payment system. Customers simply opened the Alipay app, scanned a merchant’s QR code (or displayed their personal code to be scanned by the seller), and completed the payment in seconds. This approach eliminated the need for cash, bank cards, or even point-of-sale terminals in some cases.
Beyond Convenience: Alipay’s Multifaceted Role
What sets Alipay apart from many other mobile payment tools is the sheer breadth of its functionality. The platform has evolved into a financial super-app, offering services that blur the lines between traditional banking, fintech solutions, e-commerce, lifestyle services, and even public administration. Some key functionalities include:
A. Retail and E-commerce Integration
From its origins, Alipay has been deeply intertwined with e-commerce. Users can settle transactions on Alibaba’s marketplaces and various other online platforms instantly. Additionally, merchants that operate both online and offline benefit from a unified payment solution, streamlining their payment operations and enhancing customer experience.
B. Everyday Purchases and Bills
Within a single app, users can pay for everyday needs—groceries, dining, clothing, home appliances, and more. Alipay also streamlines settling recurring bills such as utilities, mobile phone credit, and even school fees. This convenience reduces the friction of multiple logins, passwords, and separate online portals.
C. Transportation and Travel
Whether paying for a taxi, booking a train ticket, or renting a bicycle, Alipay integrates seamlessly with China’s transportation networks. Tourists can also leverage Alipay to purchase tickets for tourist attractions, simplifying travel logistics. This ease of use makes daily commutes and leisure travel more manageable.
D. Wealth Management and Insurance
Alipay’s evolution into a financial ecosystem is evident in its Yu’e Bao money market fund, which allows users to invest their idle balances into interest-bearing accounts. The app also makes it straightforward to purchase insurance policies and other financial products, transforming it into a one-stop financial management platform.
E. Public Services
Increasingly, local governments integrate public services into Alipay, enabling citizens to pay traffic fines, submit tax forms, or access public healthcare services through the platform. This integration streamlines administrative processes, aligning them with the fast-paced lifestyle of modern China.
F. International Travelers’ Access
Recognizing the importance of tourism, Alipay accommodates foreign visitors by allowing them to register accounts using their passports and link international bank cards. This thoughtful approach encourages cross-border tourism and simplifies spending for international travelers.
The Driving Forces Behind Alipay’s Popularity
The appeal of Alipay in China is rooted in several factors:
A. Unmatched Convenience
One of the most striking aspects of Alipay is its convenience. By merely scanning a QR code, users can pay for just about anything—meals, coffee, groceries, transportation, online shopping, and more. There is no more fumbling for small change, no worry about carrying physical wallets, and no delays at checkout counters. Transactions complete in seconds.
B. Speed and Efficiency
Alipay processes billions of transactions daily, and these happen nearly instantaneously. The platform’s robust technical infrastructure, supported by Alibaba’s tech prowess and cloud computing capabilities, ensures that users experience minimal downtime and seamless performance—even during high-volume periods like major shopping festivals.
C. Financial Inclusion
One of the less discussed yet highly significant impacts of Alipay is its contribution to financial inclusion. In a country as vast as China, not everyone had easy access to traditional banking services. Alipay provides an entry point for underserved populations—those who previously may not have had bank accounts or credit histories—to access financial services. Through Alipay, individuals can conduct transactions, store funds securely, pay bills, and even apply for small loans or insurance products. This democratization of financial services helps to integrate more citizens into the formal economy.
D. Data-Driven Marketing and Analytics for Merchants
For businesses, Alipay is more than just another payment channel. The platform’s integrated analytics tools help merchants understand consumer behavior, track sales, and design targeted marketing campaigns. By analyzing purchasing patterns and consumer preferences, merchants can tailor their offerings and promotions more effectively. This data-driven approach fosters closer relationships between businesses and customers.
E. Cost Savings and Operational Efficiency
Cash handling, counterfeiting, and transaction errors can be major headaches for merchants. By embracing Alipay, businesses streamline their payment processes. Without the need to handle physical money, merchants reduce the risk of employee theft, error in accounting, and the cost of handling and transporting cash. This efficiency contributes to a healthier bottom line.
F. Regulatory Environment and Government Support
The Chinese government has been supportive of digital payments, recognizing their role in driving economic growth and innovation. Regulatory frameworks have evolved to accommodate fintech solutions like Alipay. Government policies often encourage the use of digital payments for their potential to improve financial inclusion, reduce tax evasion, and stimulate domestic consumption.
Balancing Innovation and Security
Despite the many advantages of Alipay, it’s important to recognize that no digital platform is entirely free of risks. While Alipay invests heavily in security protocols—such as encryption, tokenization, and multi-factor authentication—concerns remain, especially in a landscape where technology evolves rapidly.
A. Data Privacy Concerns
With hundreds of millions of users conducting countless transactions, Alipay holds vast troves of personal and financial data. Users entrust the platform with sensitive information like ID details, transaction histories, and bank card numbers. Concerns arise around potential misuse of data, unauthorized access, and government surveillance. Alipay is tasked with continuously strengthening its data protection measures to maintain user trust.
B. System Downtime and Connectivity Issues
Relying heavily on mobile and online infrastructure means transactions are susceptible to internet connectivity problems or system maintenance downtime. If the network is weak, if the user’s smartphone battery dies, or if the platform undergoes technical issues, transactions could be delayed. Such disruptions, while not common, can be inconvenient—particularly for those who no longer carry cash as a backup.
C. Fraud and Counterfeiting Risks
QR codes, while incredibly convenient, can also be compromised. Unscrupulous individuals may print fake QR codes and affix them on payment terminals or walls to intercept user funds. Users must remain vigilant, ensuring they only scan legitimate merchant QR codes and not fall prey to scams. Alipay has introduced various security checks and features to reduce such risks, but user education is also key.
How to Mitigate Risks When Using QR Codes
While Alipay and other mobile payment platforms are relatively secure, users can take proactive steps to protect themselves. Being informed and cautious can greatly reduce the likelihood of financial loss or data theft. Here are strategies for safer digital payment practices:
A. Verify Authenticity of Merchant Codes
Always confirm that the QR code you are scanning belongs to a reputable and trustworthy merchant. A legitimate merchant’s QR code should be displayed in a stable and secure manner, often at the cashier’s desk or integrated into the official point-of-sale system. If a QR code appears tampered with or suspiciously placed, avoid scanning it.
B. Check the URL and Payment Details Before Confirming
When the Alipay app processes the QR code, it should display clear details about the merchant and the payment amount. Scrutinize these details before finalizing the transaction. If anything seems off—such as a strange merchant name, an unfamiliar URL, or an unexpected payment amount—cancel the payment and double-check with the merchant.
C. Use Built-In Scanners, Not Third-Party Apps
Rely on Alipay’s own scanning functionality rather than downloading unknown third-party QR code scanners. This approach helps ensure you are using official software protected by Alipay’s security protocols. Third-party apps could be compromised, collecting your data or redirecting you to fraudulent websites.
D. Be Wary of Unrealistic Offers
Scammers often use temptation and greed as their primary tools. If you see promotions that promise extraordinarily large returns or suspiciously generous discounts, question their legitimacy. Always verify promotional details through official channels rather than trusting unsolicited advertisements or obscure links.
E. Enable Additional Security Features
Alipay allows users to set payment limits, enable biometric authentication (fingerprint or facial recognition), and add security questions or PIN codes. Activating these features adds layers of protection, making it more challenging for unauthorized parties to use your account.
F. Stay Informed and Updated
As security threats evolve, so too do protection mechanisms. Keep your Alipay app updated to the latest version, enabling new security patches and improved encryption methods. Follow official Alipay announcements and educational materials, learning about common scams and best practices.
Alipay and the Global Trend of Mobile Payments
Alipay is not an isolated phenomenon. Other markets have seen similar growth in mobile payments, although few have reached China’s scale and sophistication. Western countries often rely more heavily on credit cards, and mobile wallets like Apple Pay and Google Pay still coexist with long-established credit and debit card infrastructures. In contrast, China’s leapfrogging from cash directly to mobile payments enabled platforms like Alipay to become embedded in the economic fabric.
Alipay’s success has also influenced neighboring countries and emerging markets, inspiring other mobile payment ecosystems. Southeast Asia, for example, has experienced a boom in mobile wallets, with local fintech startups and established players drawing lessons from China’s experiences. Alipay itself, through partnerships and investments, has sought to expand its footprint beyond China’s borders—collaborating with local payment providers to offer Chinese tourists a familiar payment environment abroad and introducing segments of its services to foreign markets.
Regulatory Compliance and the Future Landscape
No discussion of Alipay’s role would be complete without addressing the regulatory context. The Chinese government and financial regulators carefully monitor digital payment platforms like Alipay and its main competitor, WeChat Pay. Regulations cover issues ranging from data protection and anti-money laundering measures to capital requirements and transaction monitoring.
In recent years, China’s regulatory agencies have introduced measures to ensure that major fintech players like Alipay do not grow beyond effective oversight. The authorities seek to maintain financial stability, protect consumers, and encourage innovation while preventing monopolistic behaviors. These steps include requiring separate financial licenses for different types of services (such as lending or wealth management) and setting transaction limits. Alipay’s parent company, Ant Group, has faced increased regulatory scrutiny, resulting in adjustments to its corporate structure and more transparent operating procedures.
Looking ahead, as Alipay continues to refine its capabilities, we can anticipate further integration with emerging technologies. Artificial intelligence and machine learning will likely shape the platform’s fraud detection, risk assessment, and customer support features. Blockchain may enhance transparency and security in cross-border transactions and supply chain financing. Biometric authentication could become even more accurate and convenient, making transactions nearly frictionless.
Moreover, Alipay and similar platforms could accelerate the use of central bank digital currencies (CBDCs). China’s Digital Yuan initiative may eventually integrate with Alipay’s infrastructure, offering a state-backed digital currency option to users. This development could streamline monetary policy implementation, reduce transaction costs, and further cement digital payments as the default mode of commerce.
Impact on Society and Consumer Behavior
Alipay’s widespread adoption has led to profound shifts in consumer behavior. With the convenience and speed of mobile payments, Chinese consumers are more inclined to make frequent, small transactions. This encourages spontaneous purchases and fuels the growth of micro-businesses and online marketplaces. The integration of loyalty programs, discounts, and targeted marketing campaigns through Alipay can influence shopping habits and help shape a more consumer-centric economy.
Furthermore, the normalization of digital payments has social implications. Younger generations may grow up barely handling physical money, becoming accustomed to the seamless and contactless nature of transactions. Such habits could reduce petty crimes associated with cash handling, minimize the spread of germs, and encourage more transparent financial habits. However, reliance on digital platforms also means a greater dependence on technology and internet connectivity.
Case Study: Tourists and Alipay Adoption
In the past, foreign visitors to China often found it challenging to navigate the country’s cashless society. Without a Chinese bank account, tourists had limited payment options and often resorted to carrying large amounts of cash or using international credit cards, which might not be universally accepted. Recognizing the importance of tourism to the economy, Alipay introduced features allowing foreign passport holders to register for accounts. Now, visitors can link their existing credit or debit cards to Alipay, making it possible to enjoy the full spectrum of China’s mobile payment ecosystem.
This integration has transformed the tourist experience. International visitors can easily pay for museum tickets, purchase souvenirs from street vendors, or book train tickets without fussing over exchange rates or ATM withdrawals. This improved accessibility encourages repeat visits, boosts international spending, and enhances China’s appeal as a travel destination. In turn, merchants who once dealt primarily with local customers can now cater confidently to global travelers.
Merchant Perspectives: Thriving in a Cashless Economy
For merchants, adapting to Alipay has proven both a necessity and a business advantage. Traditional cash registers have given way to QR code stickers and tablets. By accepting Alipay, merchants gain access to customer bases they might otherwise miss. Integration with the platform can be seamless, and the reduced reliance on cash means fewer security concerns related to handling large sums.
Moreover, merchants gain valuable insights from Alipay’s analytics. They can track sales in real-time, analyze popular products, and adjust inventory or marketing strategies accordingly. Personalized coupons or “red envelopes” (hongbao) can be sent directly through the platform, fostering customer loyalty and engagement. This level of insight was once only available to large retailers or those with sophisticated IT departments. Now, even small businesses can harness the power of big data.
Continuous Innovation: Keeping Alipay Relevant
One reason Alipay maintains its market dominance is its commitment to continuous innovation. The company invests heavily in research and development, seeking to add new features that remain relevant as consumer preferences evolve. New partnerships with service providers, from ride-hailing giants to healthcare platforms, ensure that Alipay remains more than just a payment method—it’s an integral part of the digital lifestyle.
Additionally, Alipay experiments with user experience enhancements. Faster authentication methods, smoother integration with wearables, better voice recognition, and personalized financial advice all add layers of user satisfaction. By staying on the cutting edge, Alipay ensures that as other competitors emerge, it remains a step ahead, setting the pace for the mobile payment industry’s future evolution.
Lessons for the Global Market
Alipay’s success story offers valuable insights for other countries and regions considering a move toward cashless societies. While not all markets mirror China’s socioeconomic conditions, certain lessons apply broadly:
A. Focus on User Experience
The user interface must be intuitive and frictionless. Alipay’s simple scanning and immediate confirmation process sets a high standard for ease of use.
B. Build Trust Through Security and Reliability
From its inception, Alipay emphasized secure transactions. This foundation of trust is crucial, especially when dealing with money. Strict security measures and transparent data practices foster confidence among users.
C. Expand Beyond Payments
Offering just a payment function is no longer enough. Alipay’s ecosystem approach—integrating finance, retail, transportation, and public services—made it indispensable to everyday life.
D. Partner with Stakeholders and Regulators
Strong relationships with merchants, banks, governments, and regulators are essential. Balancing innovation with compliance builds a sustainable ecosystem.
E. Cater to a Diverse User Base
By accommodating tourists, rural populations, and unbanked customers, Alipay broadened its reach. Inclusivity ensures long-term growth and resilience against market fluctuations.
Conclusion
Alipay’s influence on the future of mobile payments in China is undeniable. By delivering convenience, financial inclusion, security, and constant innovation, the platform has woven itself into the fabric of daily life. As regulatory environments mature, technologies advance, and global markets adapt, Alipay will likely continue evolving, setting benchmarks for what is possible in a digital economy.
From facilitating instant microtransactions to offering complex financial services, Alipay has demonstrated that mobile payment platforms can be more than just a tool—they can reshape consumer behaviors, empower small businesses, and enhance national economies. While potential pitfalls around data privacy, fraud, and system reliability exist, these challenges have not deterred users from embracing the platform wholeheartedly. Instead, they highlight the need for ongoing vigilance and responsible innovation.
For tourists exploring China’s rich cultural heritage, for rural merchants seeking growth opportunities, or for everyday shoppers looking to streamline their financial lives, Alipay stands as a beacon of what modern payments can achieve. As the platform continues to adapt, it will not only reflect the shifting landscape of digital finance but also actively sculpt the contours of tomorrow’s global payment ecosystem.